
Main Line: 479.443.2705
Fax Line: 479.443.2718
Email: info@rmp.law
Bentonville – 479-553-9800
Jonesboro – 870-394-5200
Little Rock – 501-954-9000
Main Line: 479.443.2705
Fax Line: 479.443.2718
Email: info@rmp.law
Bentonville – 479-553-9800
Jonesboro – 870-394-5200
Little Rock – 501-954-9000

On Tuesday, the Federal Trade Commission issued a new Rule putting an end to employment-related non-compete clauses. In its justification for the rule, the FTC called non-compete clauses “an unfair method of competition” and stated it is a “violation for [employers] to… enter into non-compete clauses (“non-competes”) with workers.” In today’s very competitive labor market, the new FTC Rule creates a significant disruption for employers.
This new FTC provision—set to take effect in 120 days—renders existing non-compete agreements unenforceable. Existing non-compete agreements with senior executives will remain enforceable, although employers cannot require newly hired senior executives to sign such an agreement.
After the Rule takes effect, employers are required to deliver personal notice to employees (past and present) who signed a non-compete agreement informing them agreements are no longer enforceable. In the notice, employers must inform employees they are free to accept any job or start any business, even if it is directly competitive with the employer.
Compliance with the FTC Rule is not optional. Employers should consider new ways they can protect against a former employee gaining a competitive advantage by using the employer- provided training, the relationships made possible by the employer, or the confidential information learned from the employer. RMP can assist you in navigating this disruption and can provide advice on how to most effectively protect your vital business interests going forward.

RMP Attorneys At Law has an experienced Employment Law Attorney team dedicated to helping you navigate these changes. If you have any questions or would like guidance, reach out to one of our employment attorneys, Tim Hutchinson, Seth Haines, Larry McCredy, or Taylor Baltz or call 479.443.2705.
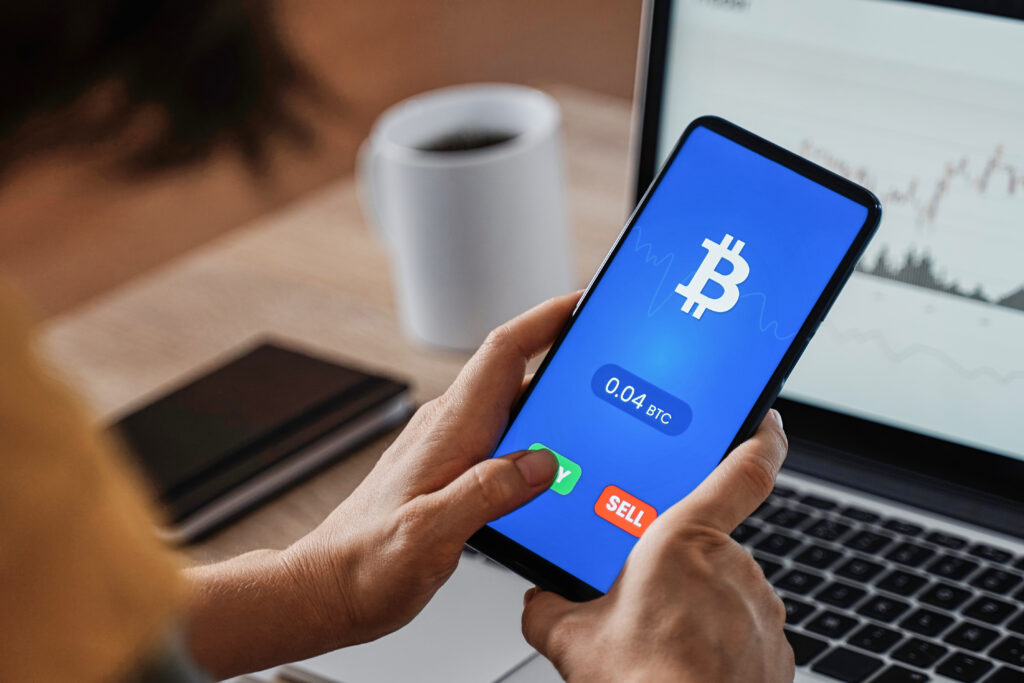
Historically, estate planning has focused mostly on bank accounts, real estate, retirement accounts, life insurance, and physical property such as family heirlooms. Today, many people also own or control valuable digital assets.
Those assets may include online financial accounts, cryptocurrency, files kept in cloud storage accounts, access to business accounts and systems, websites, domain names, social media accounts, email accounts, online photos, payment app accounts (such as PayPal or Venmo) and their balances and records, loyalty accounts, and digital records.
For Arkansas families and business owners, digital assets can create significant challenges if they are not addressed in an estate plan. Loved ones may not know what accounts and other digital assets exist. Fiduciaries may not have legal authority to access them. Passwords may be unavailable. Important financial or business information may be locked behind terms of service, two-factor authentication, or encryption.
This guide explains why digital assets matter in Arkansas estate planning and what individuals, families, and business owners should consider.
A digital asset is generally defined under the Arkansas Revised Uniform Fiduciary Access to Digital Assets Act as an electronic record in which a person has a right or interest. In everyday terms, digital assets may include online accounts, digital files, electronic records, currency, access credentials, and other property that exist in digital form.
Examples include:
Some digital assets have financial value. Others have sentimental value. Some may be essential to running a business or administering an estate.
Because of their intangible nature, digital assets can be hard to find, access, and transfer after someone dies.
A family member may know that an account exists but not have the password needed to retrieve precious photos or identify contacts who should be notified of the loved one’s death. A trustee or executor may have authority over financial assets but no practical way to access the digital records needed to identify, locate, value, and manage trust or estate property in accordance with the applicable fiduciary duties . A business partner may need access to a website, email account, payment processor, or payroll platform to keep the business running.
At the same time, in response to growing privacy concerns, companies that hold digital accounts often impose strict privacy policies and terms of service. A password alone may not be enough, and using someone else’s credentials without proper authority can create legal and practical problems.
That is why digital assets should be addressed directly in an estate plan.
Arkansas adopted a version of the Revised Uniform Fiduciary Access to Digital Assets Act in 2017. The law, codified at Ark. Code Ann. §§ 28-75-101 through 28-75-118 provides a framework for certain fiduciaries, including personal representatives, agents under powers of attorney, trustees, and guardians, to access digital assets in appropriate circumstances.
That does not mean every account can automatically be accessed. The law, the estate planning documents, the account provider’s terms, and the user’s own account settings may all matter. For example, a direction given through a provider’s online tool, such as a legacy contact or inactive account setting, can take priority over a will or trust. In addition, a fiduciary generally cannot access the content of emails and other electronic communications unless the user consented to that disclosure.
The best approach is to plan ahead by clearly giving fiduciaries authority to access digital assets, keeping a secure inventory of important accounts, and coordinating the primary estate planning documents with other estate planning tools available specifically with respect to digital assets.
Many people think of digital estate planning as deciding what happens to Facebook, Instagram, LinkedIn, or other social media accounts. Those accounts can matter a great deal, especially when they contain photos, personal messages, family memories, or professional contacts.
These accounts can also be valuable assets of the decedent’s estate in their own right, as in the case of a social media influencer whose accounts generate income.
For monetized accounts, the estate plan should address not only who will manage the account, but also who should receive ongoing revenue and handle existing sponsorship or brand agreements. Even for personal accounts, an estate plan can state whether each account should be memorialized, preserved for family, or closed, so loved ones are not left to guess.
Because many social media platforms offer legacy contact or similar tools, those settings should be used in conjunction with the estate plan so that the person designated on the platform matches the person given authority in the estate planning documents.
Cryptocurrency presents unique estate planning challenges.
Unlike some other digital assets, cryptocurrency often has significant monetary value and can be converted to cash. However, unlike a traditional bank account, cryptocurrency may not be recoverable if the private key, seed phrase, wallet access, or exchange credentials are lost. A family member may know that cryptocurrency exists but have no way to access it, and without access, its entire value may be permanently lost to the estate and its beneficiaries .
Planning for cryptocurrency starts with identifying the type of asset and documenting where it is held, whether in a personal wallet, on a hardware device, or through an exchange. Private keys and seed phrases must be protected during life but stored in a way that allows a trusted fiduciary to retrieve them after death or incapacity. Unsafe storage practices, such as keeping credentials in an unencrypted file or an email, should be avoided.
Estate planning documents should also name appropriate fiduciaries and give them the legal authority to access and manage the asset. Legal authority alone, however, does not guarantee practical access, so the plan should include secure instructions that allow fiduciaries to locate and access the asset without exposing sensitive credentials.
In every case, this requires a careful balance. The information must be secure enough to protect against theft but accessible enough that the asset is not ultimately lost.
Everyday online accounts can be just as important.
Many people receive bank statements, investment statements, tax documents, insurance notices, and bills electronically. If no one can access email or online portals, the personal representative may struggle to identify assets and debts.
Digital access may be needed to locate:
Without a plan, estate administration may take longer and cost more. The personal representative may have to piece together the decedent’s finances from paper mail, old statements, and inquiries to banks, service providers, and government agencies. These delays can increase legal and administrative fees, postpone distributions to beneficiaries, and make it harder to meet tax filing deadlines or to identify and pay debts on time.
Some business owners use a revocable living trust as part of their estate plan. If structured correctly, the tFor Arkansas business owners, digital assets may be essential to the survival of the company.
Business-related digital assets may include:
If the owner dies or becomes incapacitated, someone may need immediate access to these digital assets to keep the business operating. If no one has legal authority or practical access, the business may lose revenue, miss payroll, fail to respond to customers, lose track of tax documents or miss certain tax obligations, fall behind on vendor obligations, or lose control of important accounts.
Business owners should include digital access in both their estate plan and their business continuity plan.
The death of an LLC owner may create tax questions for the decedent’s estate, heirs, surviving owners of the business.
Depending on the circumstances, issues may include:
Business owners should not wait until after death to consider these issues. Tax planning should be coordinated with estate planning, business succession planning, and the LLC’s governing documents.
Disputes can happen when interested parties have different expectations concerning the LLC following aA common mistake is assuming that sharing passwords solves the problem.
Sharing passwords may help with the practical problem of getting into an account, but it is not a complete solution. Passwords change regularly, and even if you once shared your login information, your fiduciaries may not have the most current passwords at the time they need them. Legal authority also still matters, particularly when the fiduciary needs to take action with respect to the digital asset, such as transferring, selling, or closing it. Account providers will likely also require specific documentation before releasing information or allowing access.
For this reason, estate planning documents should be drafted to give fiduciaries appropriate authority to access, manage, copy, transfer, or close digital assets where legally permitted. Those documents should also be coordinated with any account-specific designations you have made through a provider’s online tools, such as naming a legacy contact for a social media account, so that your instructions do not conflict.
A digital asset plan should be practical, secure, and coordinated with the rest of the estate plan.
Depending on the types of digital assets you own, this plan may include:
This information must also remain secure. Login credentials, seed phrases, and account details can be misused if they fall into the wrong hands, so they should not be placed directly in a will, which may become part of the public probate record. Instead, sensitive information should be stored securely and updated separately but regularly, and named fiduciaries in the estate plan should know where to locate this information when they do ultimately need it.
Digital assets may require a fiduciary who is organized, trustworthy, and comfortable dealing with technology.
This person may need to locate digital accounts, access cloud files, manage online financial information, secure cryptocurrency information, and keep business platforms running. Throughout the process, they must protect sensitive data and preserve important records, communicate with account custodians, work with accountants or attorneys as needed, and ultimately close or memorialize accounts when appropriate. Not every executor, trustee, or agent is the right person to handle digital assets. In some cases, it may make sense to name someone with specific authority or technical ability for this part of the estate plan.
In today’s world, privacy is of the utmost concern, and digital assets are unique because they carry significant potential for privacy risks. Email accounts, text messages, cloud storage, and social media accounts may contain personal information, business records, confidential communications, family photos, and other sensitive information that needs to be preserved and protected.
For that reason, a digital asset plan must balance access with privacy. The person creating the plan may want fiduciaries to access financial records but not private communications. As noted above, a fiduciary may not be able to access the content of emails and other electronic communications without the user’s consent, so the plan should state clearly what fiduciaries may and may not see. Estate planning documents and, in some cases, provider or account settings can be used to set those limits, and they should be coordinated so they do not conflict.
Without a digital asset plan, loved ones may face a number of avoidable problems.
They may not know what accounts exist or may be unable to access financial records. Certain assets, such as family photos, important documents, and cryptocurrency may be permanently lost. Family members may struggle to close subscriptions, prevent fraud or identify theft, and administer the estate efficiently, which can add time and expense for everyone involved.
For business owners, a poorly designed digital asset plan, or no plan at all, can threaten the business itself . A company may lose control of its website, email, payment systems, advertising accounts, or client records, putting revenue, customer relationships, and the continuity of the business at risk.
Common mistakes include:
These mistakes can make an already difficult time more stressful.
Digital asset planning matters not only after death but also during life, if you become unable to manage your own affairs. If you become seriously ill or injured, a trusted agent may need access to your online accounts to pay bills, manage business obligations, collect records, file taxes, or protect assets.
Whether that agent has authority depends on which document controls which assets, and when. A will controls assets in your individual name only after death. A trust controls assets owned by the trust, and a successor trustee can generally manage those assets if you become incapacitated as well as after your death. A financial power of attorney, by contrast, controls assets held in your individual name during your lifetime, including during incapacity, and it ends at death.
This distinction is especially important for digital assets. Because online accounts are typically opened, and the provider’s terms of service agreed to, by an individual user, most digital assets are held in your individual name rather than in a trust.
For that reason, your financial power of attorney should be reviewed to make sure it includes appropriate digital asset authority. Business owners, in particular, should consider who can access company systems if they are unavailable.
When reviewing your estate plan and digital asset, consider these questions:
If you are unsure how to answer several of these questions, it may be time to update your estate plan.
Now more than ever, digital assets are part of everyday life, and as more of our financial, personal, and business lives move online, planning for them becomes more important with each passing day.
Without a plan, those assets can be difficult or impossible to access. This can delay probate, complicate trust administration, create business problems, and increase stress for loved ones.
A thoughtful estate plan should account for both traditional assets and digital ones.
Because nearly everyone now has some form of digital assets, every estate plan should address them. If your current will, trust, or power of attorney was prepared before digital assets became a part of your life, or does not specifically mention them, it may be time for an update. If you are unsure whether your documents address digital assets, or if you have specific concerns about the privacy or security of your accounts or about who will be able to access them, you may wish to seek guidance from an estate planning attorney.
Updating your plan is especially important if you own cryptocurrency or other digital assets with significant value, or if you run a business that depends on digital accounts or cloud-based systems. In these situations, an Arkansas estate planning attorney can help make sure the right people have both the legal authority and the practical ability to manage your digital assets when it matters most.
Legal guidance can also be valuable if you are serving as an executor, trustee, or other fiduciary and need access to someone else’s digital records. An attorney can help you understand what you are permitted to do under Arkansas law and carry out your duties with confidence.
RMP Law assists Arkansas individuals and families, business owners, and fiduciaries with estate planning, probate, trust administration, business succession planning, and related legal matters.
If you have questions about digital assets and estate planning in Arkansas, contact RMP Law at 479-443-2705 or use our Message Us form.
Main RMP Number: 479-443-2705
Bentonville – 479-553-9800
Jonesboro – 870-394-5200
Little Rock – 501-954-9000

DISCLAIMER: The information provided on this website does not constitute legal advice. Instead, all information, content, and materials available on this site are for general informational purposes. Information on this website may not constitute the most up-to-date legal or other information. Readers of this website should contact their attorney to obtain advice with respect to any particular legal matter.
Historically, estate planning has focused mostly on bank accounts, real estate, retirement accounts, life insurance, and physical property such as family heirlooms. Today, many people also own or control valuable digital assets.
Those assets may include online financial accounts, cryptocurrency, files kept in cloud storage accounts, access to business accounts and systems, websites, domain names, social media accounts, email accounts, online photos, payment app accounts (such as PayPal or Venmo) and their balances and records, loyalty accounts, and digital records.
For Arkansas families and business owners, digital assets can create significant challenges if they are not addressed in an estate plan. Loved ones may not know what accounts and other digital assets exist. Fiduciaries may not have legal authority to access them. Passwords may be unavailable. Important financial or business information may be locked behind terms of service, two-factor authentication, or encryption.
This guide explains why digital assets matter in Arkansas estate planning and what individuals, families, and business owners should consider.
A digital asset is generally defined under the Arkansas Revised Uniform Fiduciary Access to Digital Assets Act as an electronic record in which a person has a right or interest. In everyday terms, digital assets may include online accounts, digital files, electronic records, currency, access credentials, and other property that exist in digital form.
Examples include:
Some digital assets have financial value. Others have sentimental value. Some may be essential to running a business or administering an estate.
Because of their intangible nature, digital assets can be hard to find, access, and transfer after someone dies.
A family member may know that an account exists but not have the password needed to retrieve precious photos or identify contacts who should be notified of the loved one’s death. A trustee or executor may have authority over financial assets but no practical way to access the digital records needed to identify, locate, value, and manage trust or estate property in accordance with the applicable fiduciary duties . A business partner may need access to a website, email account, payment processor, or payroll platform to keep the business running.
At the same time, in response to growing privacy concerns, companies that hold digital accounts often impose strict privacy policies and terms of service. A password alone may not be enough, and using someone else’s credentials without proper authority can create legal and practical problems.
That is why digital assets should be addressed directly in an estate plan.
Arkansas adopted a version of the Revised Uniform Fiduciary Access to Digital Assets Act in 2017. The law, codified at Ark. Code Ann. §§ 28-75-101 through 28-75-118 provides a framework for certain fiduciaries, including personal representatives, agents under powers of attorney, trustees, and guardians, to access digital assets in appropriate circumstances.
That does not mean every account can automatically be accessed. The law, the estate planning documents, the account provider’s terms, and the user’s own account settings may all matter. For example, a direction given through a provider’s online tool, such as a legacy contact or inactive account setting, can take priority over a will or trust. In addition, a fiduciary generally cannot access the content of emails and other electronic communications unless the user consented to that disclosure.
The best approach is to plan ahead by clearly giving fiduciaries authority to access digital assets, keeping a secure inventory of important accounts, and coordinating the primary estate planning documents with other estate planning tools available specifically with respect to digital assets.
Many people think of digital estate planning as deciding what happens to Facebook, Instagram, LinkedIn, or other social media accounts. Those accounts can matter a great deal, especially when they contain photos, personal messages, family memories, or professional contacts.
These accounts can also be valuable assets of the decedent’s estate in their own right, as in the case of a social media influencer whose accounts generate income.
For monetized accounts, the estate plan should address not only who will manage the account, but also who should receive ongoing revenue and handle existing sponsorship or brand agreements. Even for personal accounts, an estate plan can state whether each account should be memorialized, preserved for family, or closed, so loved ones are not left to guess.
Because many social media platforms offer legacy contact or similar tools, those settings should be used in conjunction with the estate plan so that the person designated on the platform matches the person given authority in the estate planning documents.
Cryptocurrency presents unique estate planning challenges.
Unlike some other digital assets, cryptocurrency often has significant monetary value and can be converted to cash. However, unlike a traditional bank account, cryptocurrency may not be recoverable if the private key, seed phrase, wallet access, or exchange credentials are lost. A family member may know that cryptocurrency exists but have no way to access it, and without access, its entire value may be permanently lost to the estate and its beneficiaries .
Planning for cryptocurrency starts with identifying the type of asset and documenting where it is held, whether in a personal wallet, on a hardware device, or through an exchange. Private keys and seed phrases must be protected during life but stored in a way that allows a trusted fiduciary to retrieve them after death or incapacity. Unsafe storage practices, such as keeping credentials in an unencrypted file or an email, should be avoided.
Estate planning documents should also name appropriate fiduciaries and give them the legal authority to access and manage the asset. Legal authority alone, however, does not guarantee practical access, so the plan should include secure instructions that allow fiduciaries to locate and access the asset without exposing sensitive credentials.
In every case, this requires a careful balance. The information must be secure enough to protect against theft but accessible enough that the asset is not ultimately lost.
Everyday online accounts can be just as important.
Many people receive bank statements, investment statements, tax documents, insurance notices, and bills electronically. If no one can access email or online portals, the personal representative may struggle to identify assets and debts.
Digital access may be needed to locate:
Without a plan, estate administration may take longer and cost more. The personal representative may have to piece together the decedent’s finances from paper mail, old statements, and inquiries to banks, service providers, and government agencies. These delays can increase legal and administrative fees, postpone distributions to beneficiaries, and make it harder to meet tax filing deadlines or to identify and pay debts on time.
Some business owners use a revocable living trust as part of their estate plan. If structured correctly, the tFor Arkansas business owners, digital assets may be essential to the survival of the company.
Business-related digital assets may include:
If the owner dies or becomes incapacitated, someone may need immediate access to these digital assets to keep the business operating. If no one has legal authority or practical access, the business may lose revenue, miss payroll, fail to respond to customers, lose track of tax documents or miss certain tax obligations, fall behind on vendor obligations, or lose control of important accounts.
Business owners should include digital access in both their estate plan and their business continuity plan.
The death of an LLC owner may create tax questions for the decedent’s estate, heirs, surviving owners of the business.
Depending on the circumstances, issues may include:
Business owners should not wait until after death to consider these issues. Tax planning should be coordinated with estate planning, business succession planning, and the LLC’s governing documents.
Disputes can happen when interested parties have different expectations concerning the LLC following aA common mistake is assuming that sharing passwords solves the problem.
Sharing passwords may help with the practical problem of getting into an account, but it is not a complete solution. Passwords change regularly, and even if you once shared your login information, your fiduciaries may not have the most current passwords at the time they need them. Legal authority also still matters, particularly when the fiduciary needs to take action with respect to the digital asset, such as transferring, selling, or closing it. Account providers will likely also require specific documentation before releasing information or allowing access.
For this reason, estate planning documents should be drafted to give fiduciaries appropriate authority to access, manage, copy, transfer, or close digital assets where legally permitted. Those documents should also be coordinated with any account-specific designations you have made through a provider’s online tools, such as naming a legacy contact for a social media account, so that your instructions do not conflict.
A digital asset plan should be practical, secure, and coordinated with the rest of the estate plan.
Depending on the types of digital assets you own, this plan may include:
This information must also remain secure. Login credentials, seed phrases, and account details can be misused if they fall into the wrong hands, so they should not be placed directly in a will, which may become part of the public probate record. Instead, sensitive information should be stored securely and updated separately but regularly, and named fiduciaries in the estate plan should know where to locate this information when they do ultimately need it.
Digital assets may require a fiduciary who is organized, trustworthy, and comfortable dealing with technology.
This person may need to locate digital accounts, access cloud files, manage online financial information, secure cryptocurrency information, and keep business platforms running. Throughout the process, they must protect sensitive data and preserve important records, communicate with account custodians, work with accountants or attorneys as needed, and ultimately close or memorialize accounts when appropriate. Not every executor, trustee, or agent is the right person to handle digital assets. In some cases, it may make sense to name someone with specific authority or technical ability for this part of the estate plan.
In today’s world, privacy is of the utmost concern, and digital assets are unique because they carry significant potential for privacy risks. Email accounts, text messages, cloud storage, and social media accounts may contain personal information, business records, confidential communications, family photos, and other sensitive information that needs to be preserved and protected.
For that reason, a digital asset plan must balance access with privacy. The person creating the plan may want fiduciaries to access financial records but not private communications. As noted above, a fiduciary may not be able to access the content of emails and other electronic communications without the user’s consent, so the plan should state clearly what fiduciaries may and may not see. Estate planning documents and, in some cases, provider or account settings can be used to set those limits, and they should be coordinated so they do not conflict.
Without a digital asset plan, loved ones may face a number of avoidable problems.
They may not know what accounts exist or may be unable to access financial records. Certain assets, such as family photos, important documents, and cryptocurrency may be permanently lost. Family members may struggle to close subscriptions, prevent fraud or identify theft, and administer the estate efficiently, which can add time and expense for everyone involved.
For business owners, a poorly designed digital asset plan, or no plan at all, can threaten the business itself . A company may lose control of its website, email, payment systems, advertising accounts, or client records, putting revenue, customer relationships, and the continuity of the business at risk.
Common mistakes include:
These mistakes can make an already difficult time more stressful.
Digital asset planning matters not only after death but also during life, if you become unable to manage your own affairs. If you become seriously ill or injured, a trusted agent may need access to your online accounts to pay bills, manage business obligations, collect records, file taxes, or protect assets.
Whether that agent has authority depends on which document controls which assets, and when. A will controls assets in your individual name only after death. A trust controls assets owned by the trust, and a successor trustee can generally manage those assets if you become incapacitated as well as after your death. A financial power of attorney, by contrast, controls assets held in your individual name during your lifetime, including during incapacity, and it ends at death.
This distinction is especially important for digital assets. Because online accounts are typically opened, and the provider’s terms of service agreed to, by an individual user, most digital assets are held in your individual name rather than in a trust.
For that reason, your financial power of attorney should be reviewed to make sure it includes appropriate digital asset authority. Business owners, in particular, should consider who can access company systems if they are unavailable.
When reviewing your estate plan and digital asset, consider these questions:
If you are unsure how to answer several of these questions, it may be time to update your estate plan.
Now more than ever, digital assets are part of everyday life, and as more of our financial, personal, and business lives move online, planning for them becomes more important with each passing day.
Without a plan, those assets can be difficult or impossible to access. This can delay probate, complicate trust administration, create business problems, and increase stress for loved ones.
A thoughtful estate plan should account for both traditional assets and digital ones.
Because nearly everyone now has some form of digital assets, every estate plan should address them. If your current will, trust, or power of attorney was prepared before digital assets became a part of your life, or does not specifically mention them, it may be time for an update. If you are unsure whether your documents address digital assets, or if you have specific concerns about the privacy or security of your accounts or about who will be able to access them, you may wish to seek guidance from an estate planning attorney.
Updating your plan is especially important if you own cryptocurrency or other digital assets with significant value, or if you run a business that depends on digital accounts or cloud-based systems. In these situations, an Arkansas estate planning attorney can help make sure the right people have both the legal authority and the practical ability to manage your digital assets when it matters most.
Legal guidance can also be valuable if you are serving as an executor, trustee, or other fiduciary and need access to someone else’s digital records. An attorney can help you understand what you are permitted to do under Arkansas law and carry out your duties with confidence.
RMP Law assists Arkansas individuals and families, business owners, and fiduciaries with estate planning, probate, trust administration, business succession planning, and related legal matters.
If you have questions about digital assets and estate planning in Arkansas, contact RMP Law at 479-443-2705 or use our Message Us form.
Main RMP Number: 479-443-2705
Bentonville – 479-553-9800
Jonesboro – 870-394-5200
Little Rock – 501-954-9000
DISCLAIMER: The information provided on this website does not constitute legal advice. Instead, all information, content, and materials available on this site are for general informational purposes. Information on this website may not constitute the most up-to-date legal or other information. Readers of this website should contact their attorney to obtain advice with respect to any particular legal matter.

Main Line: 479.443.2705
Fax Line: 479.443.2718
Email: info@rmp.law
Bentonville – 479-553-9800
Jonesboro – 870-394-5200
Little Rock – 501-954-9000
JOHNSON
5519 Hackett Street, Suite 300
Springdale, AR 72762
BENTONVILLE
809 SW A Street, Suite 105
Bentonville, AR 72712
JONESBORO
710 Windover Road, Suite B
Jonesboro, AR 72401
LITTLE ROCK
17901 Chenal Parkway, Suite 200
Little Rock, AR 72223